 Facebook
 X
 Pinterest
 Copy Link
Does the Fed Control Mortgage Rates?
You have probably seen a headline saying the Federal Reserve raised rates and assumed mortgage rates just went up because of it.
That is an easy connection to make, but it is not quite how it works.
The Fed does not set mortgage rates. It sets a short-term policy rate called the federal funds rate. Mortgage rates are influenced by a much larger mix of factors, including inflation, the economy, the bond market, and what investors expect to happen next.
The Fed certainly influences that environment, but a Fed rate increase does not automatically mean mortgage rates rise by the same amount.
Where Mortgage Rates Are Right Now
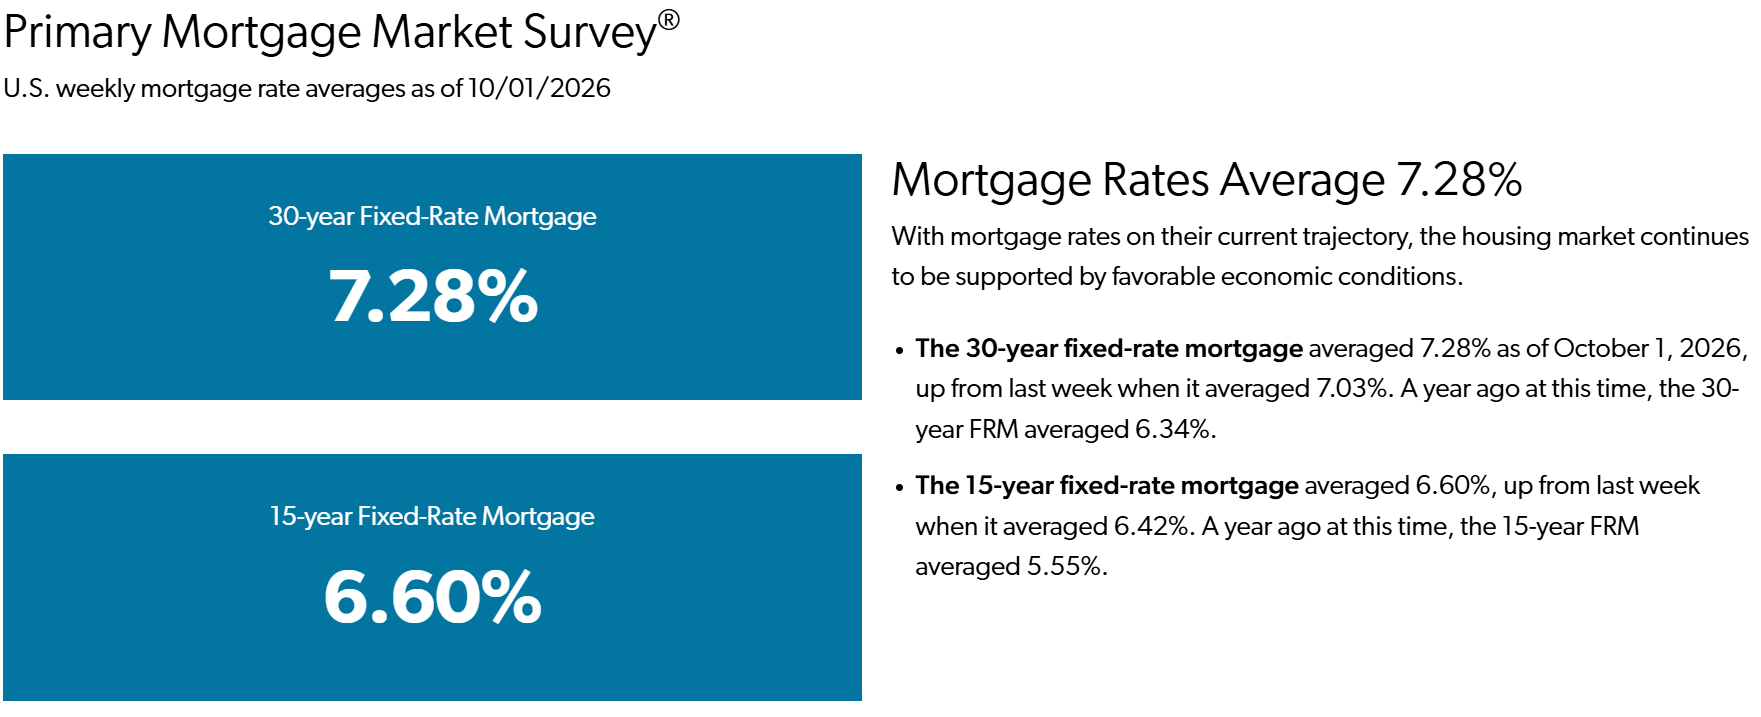
Source: Freddie Mac Primary Mortgage Market Survey®, October 1, 2026.
On September 16, the Federal Reserve raised its target rate by one-quarter of a percentage point as it continued working to bring inflation under control.
Meanwhile, Freddie Mac reported that the average 30-year fixed mortgage rate was 7.28% as of October 1, 2026, up from 7.03% the week before and 6.34% a year earlier.
That 7.28% is a national benchmark, not a quote for every buyer. Freddie Mac’s survey focuses on conventional, conforming loans for borrowers with 20% down and excellent credit. The actual rate available to a buyer depends on the borrower, loan program, down payment, credit, lender, and other factors.
But Affordability Is About More Than the Rate
This is where I think the conversation gets more practical.
I work with a lot of first-time homebuyers. Most are not studying interest-rate history or trying to decide whether 7.1% is better than rates from ten years ago.
They are looking at their own numbers and asking:
Can I afford to buy this house?
For many of the buyers I talk with, the biggest hurdle is actually the cash needed for the down payment and closing costs. For others, the monthly payment is the number they simply cannot cross.
I recently worked with a first-time buyer who had enough money set aside for her down payment and closing costs, but she also had a firm monthly budget she needed to stay within.
We negotiated seller concessions, and she worked with her lender to use those funds toward a permanent rate buydown. That helped make the payment work for her situation.
That will not be the right solution for every buyer, but it is a good example of why affordability is bigger than one interest-rate number.
Purchase price, down payment, closing costs, property taxes, insurance, financing options, seller concessions, and your own comfort level all matter.
What Is Happening in Arlington?
The latest complete Arlington market numbers are from August 2026.
According to the MetroTex Association of REALTORS®:
- Median sales price: $320,000
- Median days on market: 49 days
- Months of inventory: 3.5 months
- Ratio to original list price: 95.7%
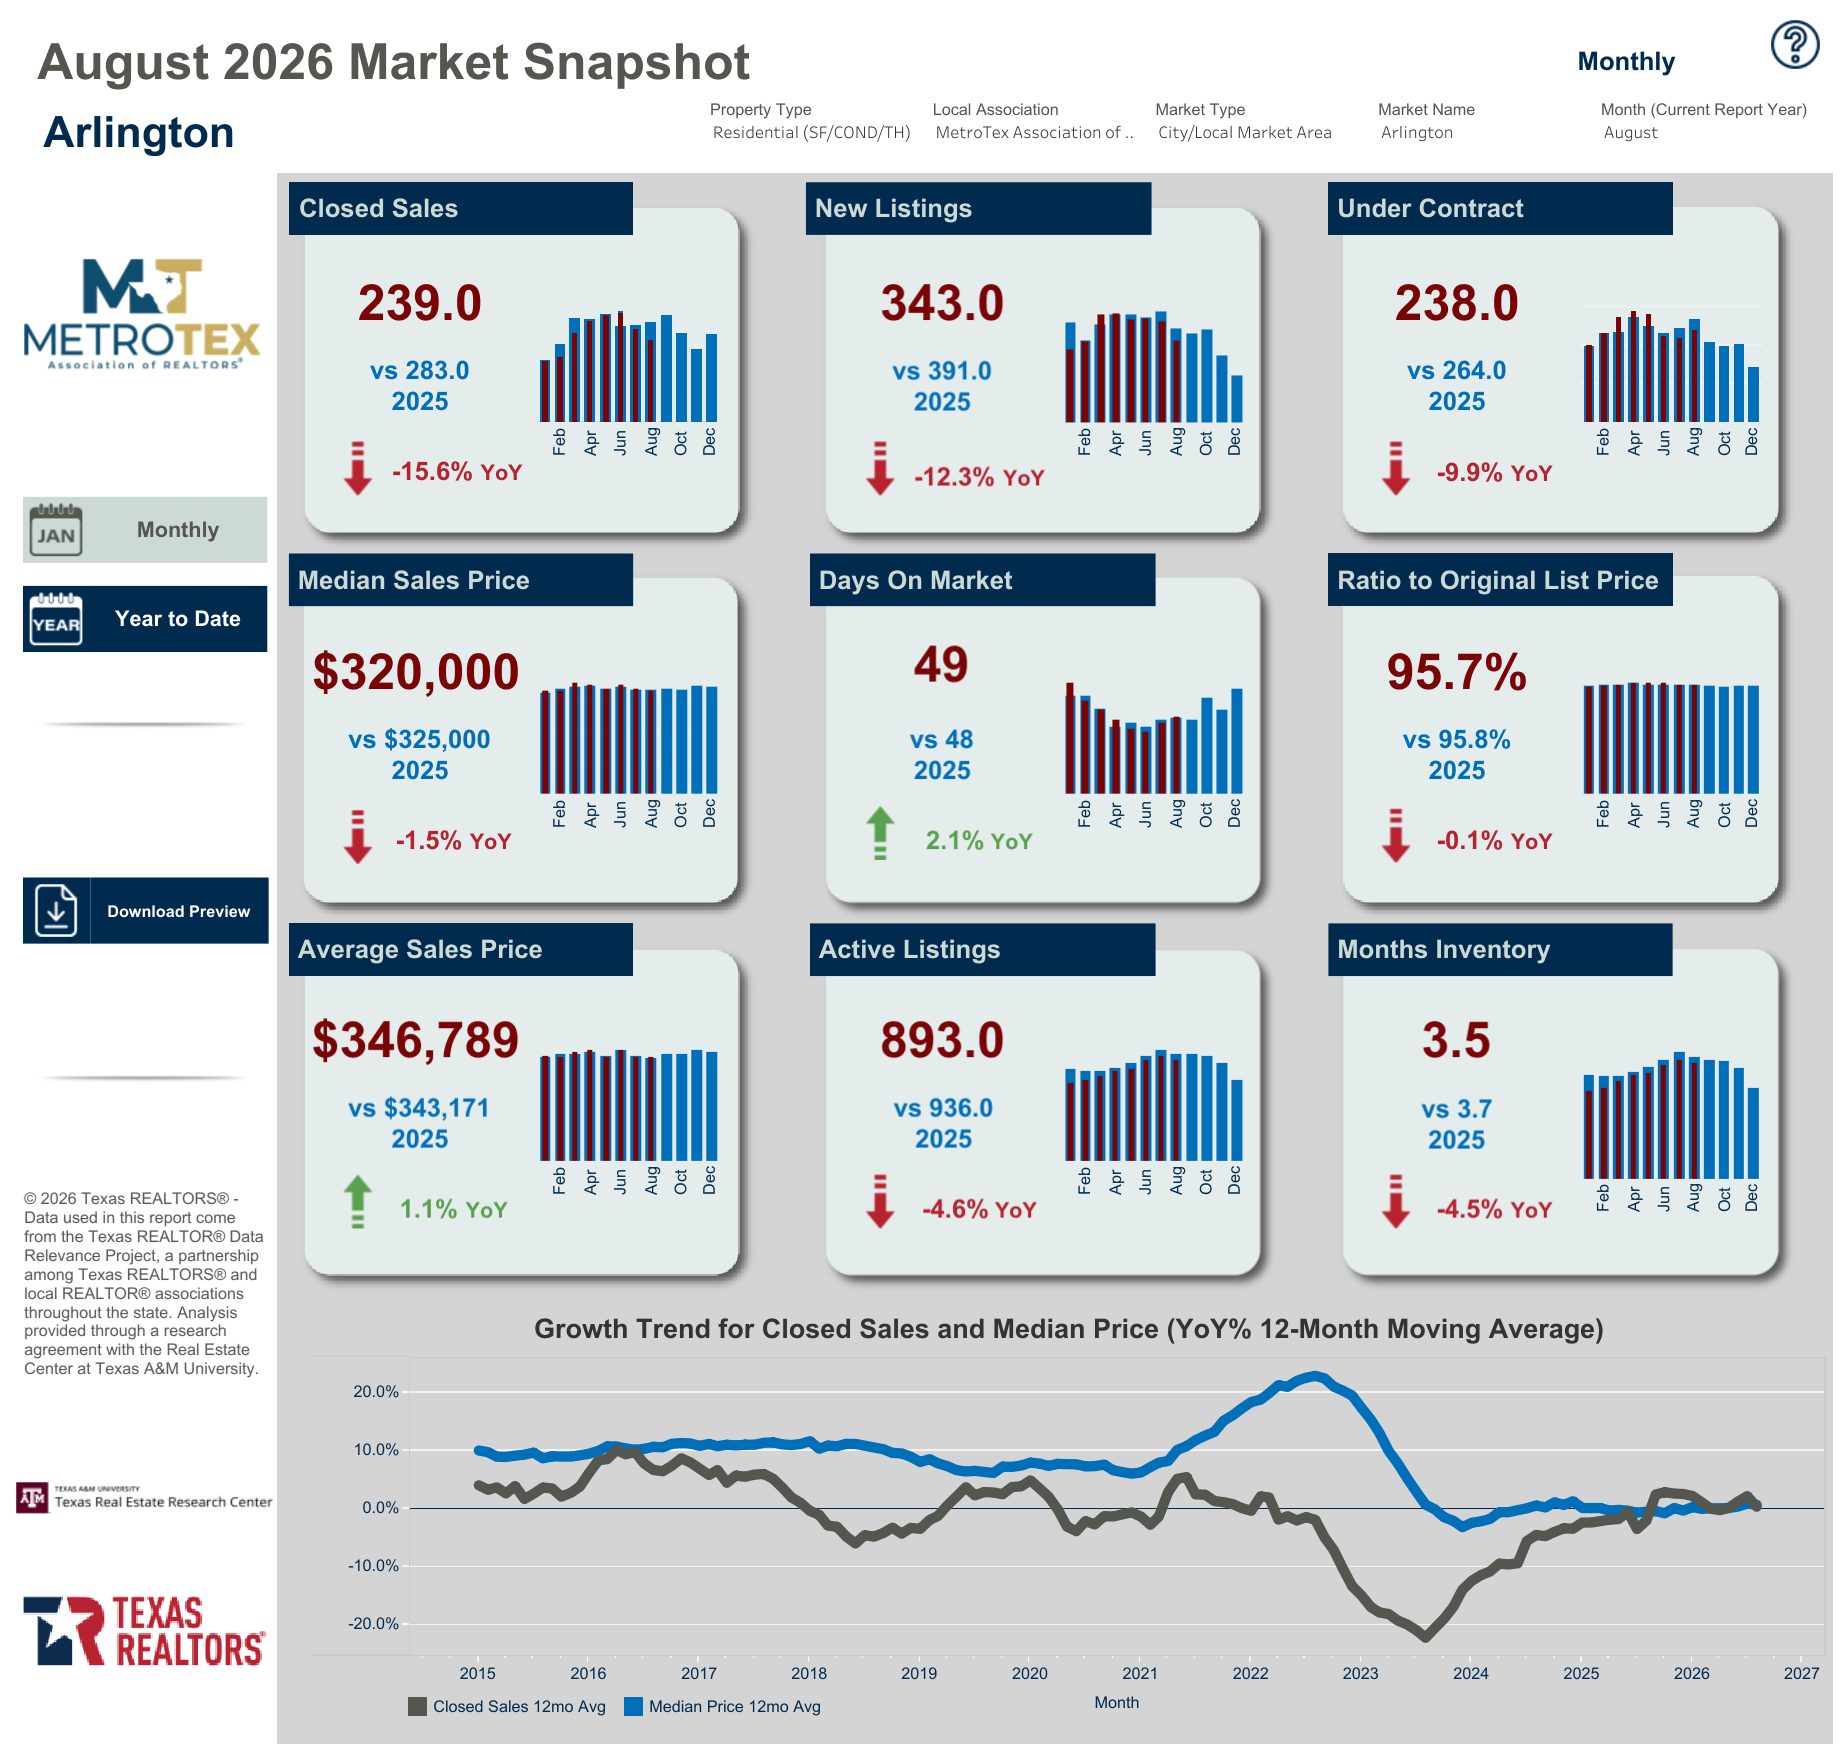
Source: MetroTex Association of REALTORS®, August 2026 Arlington Market Snapshot.
Those numbers do not mean every seller will negotiate. They do tell us that buyers and sellers need to look at the individual property instead of assuming every home will sell immediately at the original asking price.
A home that has been sitting for several weeks may create a very different negotiating opportunity than a new listing with strong activity.
What This Means for Buyers
Start with your actual budget, not the rate you saw in a headline.
A good lender can help you understand your payment, cash needed to close, and financing options. Getting pre-approved gives us real numbers to work with before we start shopping. If you are not sure what pre-approval involves or why it matters, I put together a short guide: Why Pre-Approval Comes First.
Then we can look at the house and the market around it. Depending on the property and seller, there may be opportunities to negotiate price, closing costs, seller concessions, or other terms.
The goal is not to predict where mortgage rates will go next.
The goal is to find out whether buying makes sense for your situation today.
What This Means for Sellers
Higher mortgage rates affect what many buyers can comfortably afford, even though the Fed does not directly set those rates.
That makes pricing and negotiation important.
Sometimes a buyer may benefit more from help with closing costs or another negotiated concession than from a similar reduction in price. Other times, price really is the issue.
We have to look at your home, the competition, buyer response, and what you need the sale to accomplish.
The Bottom Line
The Fed matters, but it does not control your mortgage rate.
And your mortgage rate matters, but it is only one part of affordability.
If you are thinking about buying or selling in Arlington or the DFW area, I would be glad to help you look at the market, your options, and what makes sense for your situation.
Visit rob-hurt.com to get started.


